For buyers and owners planning to extend
Remortgage for Home Improvements: Buy, Extend, Then Release Equity
Sviatoslav JerdetchiiCEO & Founder of Craftex. Updated , 11 min read
The short answer
You can remortgage for home improvements, but only in the order lenders accept: buy, build, get sign-off, then revalue. Our 2026 London rates run from about £1,685 per m² for a rear dormer loft to £2,880 per m² for a double-storey extension, ex VAT and fees.
- Fund the works first: cash, a further advance from your lender, or a loan. The remortgage on the new value comes after.
- Many lenders want six months of ownership before a remortgage, and leaving a fixed rate early can cost 1% to 5% of the balance.
- A loft or extension with a double bedroom and bathroom can add up to 24% to a three-bedroom house (Nationwide, October 2025).
- At the same loan-to-value you borrow back about three quarters of the uplift, so the uplift has to beat the cost.
You can remortgage for home improvements, but in the order lenders accept: buy, build, get sign-off, then revalue. Our 2026 London rates are about £1,685 to £1,980 per m² for a rear dormer loft. A kitchen extension is £2,140 to £2,520 per m², ex VAT and fees.
A 30 m² loft with a double bedroom and bathroom therefore costs about £50,000 to £59,000 to build. Nationwide's October 2025 analysis puts the value it can add to a three-bedroom house at up to 24%.
The plan our clients ask about is simple. Buy a house with room to grow, extend it, ask the lender for a new valuation, and remortgage to release the equity. It works when the numbers and the timing are right. It fails when they are not.
This guide checks each step against the lending rules: the six-month rule, early repayment charges, affordability and valuation. Then it runs a worked example on a £1M house. We write it as the builder who prices and builds the house extension, not as a broker.
This article is general information, not financial advice. Speak to an FCA-regulated mortgage adviser before you borrow. If you are viewing a house now, check what your house can add before you offer.
How remortgaging for home improvements works, step by step
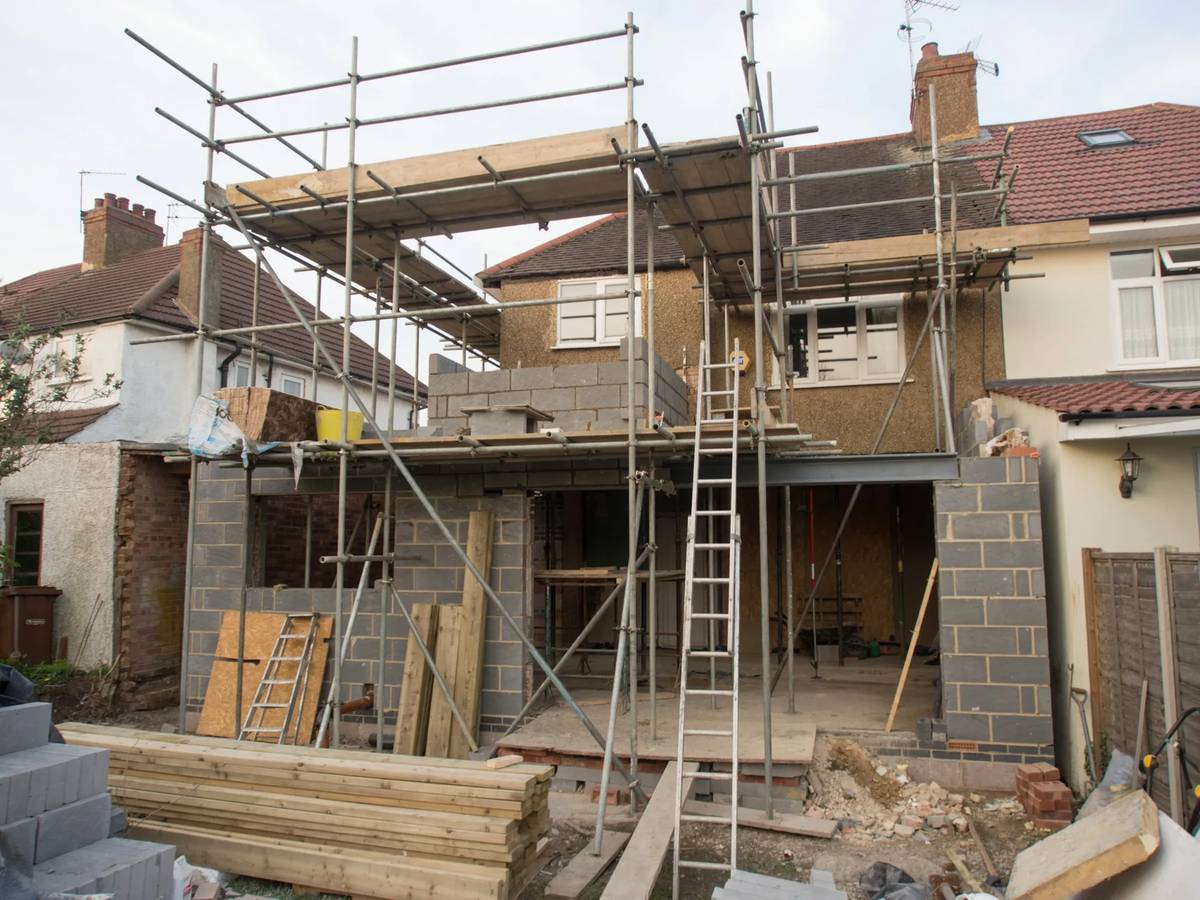
Remortgaging for home improvements is a sequence, not a single loan. The lender lends against what the house is worth on the day its valuer inspects, so the extra value has to exist first.
- Buy. You complete with a normal purchase mortgage. Stamp duty is paid once, here, on the price you pay.
- Fund the works. Savings, a further advance from your lender, or a secured or unsecured loan pay the builder.
- Build and sign off. The works finish, building control issues a completion certificate, and you keep the planning or permitted development evidence.
- Revalue. The lender's valuer inspects the finished house and compares it with sold homes nearby.
- Remortgage or borrow more. You refinance against the new value, at a loan-to-value the lender accepts, and pass its affordability check.
Which extensions add value, and what they cost
Not every square metre is worth the same. Space that adds a bedroom, or a bedroom with its own bathroom, moves the price most. A bigger kitchen adds appeal, but buyers count bedrooms first.

The table sets out the usual options on a London house, the consent route and our 2026 build rates. The rates cover construction only, ex VAT and fees.
| Option | Usual consent route | Our 2026 rate per m² | What it adds |
|---|---|---|---|
| Side return or rear kitchen extension | Permitted development within the limits, or prior approval | £2,140 to £2,520 | Space, no extra bedroom |
| Double-storey rear extension | Planning permission in most London cases | £2,450 to £2,880 | A bedroom upstairs |
| Rear dormer loft conversion | Permitted development, outside conservation areas | £1,685 to £1,980 | Bedroom and bathroom |
| Hip-to-gable loft conversion | Permitted development, outside conservation areas | £1,915 to £2,250 | Bedroom and bathroom |
| Mansard or rooftop storey | Planning permission, as a rule | £2,295 to £2,700 | One or two bedrooms |
| New basement under the house | Planning permission in most boroughs, plus party wall | £2,295 to £2,700 | Living space, sometimes a bedroom |
Basement rates cover the finished floor. Excavation, underpinning and groundwater are priced after the survey, and they often decide the total. Our guides to house extension cost, loft conversion cost and basement conversion cost break each one down.
The value uplift: what the evidence says
The most recent lender study we found is Nationwide's, published in October 2025. It is 13 months old. It used Nationwide's own house price data from October 2024 to September 2025.
Three findings matter for the plan. A 10% increase in floor space adds about 5% to a typical house. An extra bedroom adds more: 10% for a terraced or semi-detached house going from three bedrooms to four, 13% for a detached one.
The headline is the bedroom and bathroom together. Nationwide assumed 28 m² of new floor area for that figure, about the size of a good rear dormer loft.
The street ceiling price
Every street has a price that buyers will not go past, however good the house. A £1M house on a street where the best house sold for £1.1M cannot be valued at £1.3M. The valuer works from sold comparables, not from what you spent.
Before you offer, look up sold prices for the same house type on the same street, with one bedroom more. Divide each price by its floor area from the energy certificate. If that figure per m² is well above our build rate, the extension has room to add value. If it is close, the uplift may not cover the cost.
Permitted development, planning and the paperwork a valuer wants
The consent route decides the timeline and the risk. Permitted development lets you build without a planning application, within fixed limits. Outside them you need planning permission, which takes longer and can be refused.

The main limits, from the General Permitted Development Order:
- Single-storey rear. Up to 3 m deep on a terraced or semi-detached house, 4 m detached, and 4 m high. Prior approval stretches that to 6 m and 8 m, outside conservation areas.
- Side return. Single storey, up to 4 m high and no wider than half the original house. Not allowed in a conservation area.
- Two-storey rear. Up to 3 m deep and at least 7 m from the rear boundary. Not allowed in a conservation area.
- Loft. Up to 40 m³ of extra roof space on a terraced house, 50 m³ on others. Not on the front roof slope facing the road, and not in a conservation area.
- Extra storeys. Class AA allows upward extensions with prior approval, but not on houses built before 1 July 1948. That rules out most Victorian and Edwardian terraces.
A conservation area, or an Article 4 direction from the council, removes some or all of these rights. Many inner London streets have one, which is why mansards there go through a full planning application. The householder application fee in England is £548 from April 2026.
The papers that turn work into value
A valuer and a lender's conveyancer look for evidence, not effort. Keep each of these in one file:
- Planning permission or a lawful development certificate. A certificate proves the work was permitted development.
- Building control completion certificate. On full plans it usually follows within eight weeks of finishing, if the work complies.
- Party wall awards. Notice for work on a shared wall goes out at least two months before it starts. Digging near a neighbour's foundations triggers notice too.
- Certificates and warranties. Electrical certificate, glazing and structural guarantees.
GOV.UK puts it plainly: without building regulations approval you will not have the certificates you may need when you sell. A valuer reads a missing certificate the same way.
How to fund the works after you buy
The money for the build has to exist before the house is worth more. There are five ways to find it, and they differ in cost, speed and risk.
| Route | How it works | Watch out for |
|---|---|---|
| Savings | You pay the builder in stages from cash | Leaves less buffer for overruns |
| Further advance | Your current lender adds to the mortgage for home improvements | Full affordability check; often a separate rate |
| Remortgage to a new lender | You move the whole loan and borrow more | Six-month rule, early repayment charge |
| Secured loan on the home | A second loan behind your mortgage | Usually dearer; your home is at risk |
| Unsecured personal loan | Borrowing not tied to the house | Smaller sums, shorter terms |
A further advance is the route most owners try first, because it avoids the switch. The FCA rules exempt a lender from a new affordability assessment only when there is no extra borrowing. A further advance is extra borrowing, so your income is checked again.
If the house is unmortgageable when you buy it, or the work is heavy, the route is different again. A refurbishment bridging loan buys and funds the works, and a mortgage on the new value repays it. Our guide to renovation mortgages and refurbishment loans explains that route and its paperwork.
I and my husband are very satisfied with Craftex's service and customer support. We bought a house in Hampstead and wanted to redesign and renovate it. On our initial free consultation with Sviat, we found out that we actually can do loft conversion and rear extension and add value to the property straight away. We worked with the Craftex design team to bring our vision to life and deliver planning approvals. At that time guys started stripping out to save time on the construction programme as we wanted to move in ASAP. We worked with very experienced project director Konstantin who was responsible for all aspects of project delivery from design to construction with a very good eye on details and customer care. We saved a lot of money by having professional advice from the start. Project management and quality at Craftex are at the highest level. Many thanks to Craftex Team.
Remortgaging on the new value: the rules that set the timing
Three rules decide when the remortgage can happen and what it releases. None of them is in the headline plan, and each can cost money.
The six-month rule
Many lenders will not accept a remortgage until you have owned the property for six months. A building society's criteria say exactly that: remortgages are considered after six months' ownership. A high-street bank's criteria require the property to be in your name for at least six months.
Some lenders will lend on a value raised by refurbishment once you pass six months, subject to the valuer. In practice the build takes longer than six months anyway, so plan the remortgage for after sign-off, not after purchase.
Early repayment charges
Most fixed and discounted rates carry an early repayment charge if you repay the loan during the deal. A building society's guide puts it at 1% to 5% of the balance. On a £750,000 mortgage that is £7,500 to £37,500.
Two ways around it: borrow more from your current lender, or buy on a deal whose charges end before the works do. Choose this when you take the purchase mortgage, not after.
Affordability and rate stress
The lender lends against income as well as value. Under the FCA's rules it must assess whether you can pay, and allow for likely rate rises over at least five years. That stress test does not apply where the rate is fixed for five years or more.
A worked example: a £1M house, a loft and a kitchen extension
This example is illustrative, not advice. It uses our 2026 rates for the works and Nationwide's October 2025 figures for the uplift. Your lender, your income and your street will change every number.
The house: a three-bedroom, one-bathroom London terrace bought for £1,000,000 as a home, with a 25% deposit. The works: a 30 m² rear dormer loft with a double bedroom and bathroom, and a 20 m² side return kitchen extension.
| Item | Figure |
|---|---|
| Purchase price | £1,000,000 |
| Mortgage at 75% loan-to-value | £750,000 |
| Stamp duty, paid once at purchase (only home) | £43,750 |
| Loft, 30 m² at our rear dormer rate, ex VAT | £50,000 to £59,000 |
| Kitchen extension, 20 m² at our kitchen rate, ex VAT | £43,000 to £50,000 |
| Works budget used below: top of both ranges, plus VAT, a 10% contingency and an assumed £15,000 for design, engineer, approvals and party wall surveyors | about £160,000 |
The £160,000 is paid from savings in this example. Then, after sign-off and more than six months of ownership, the lender revalues the house. The table shows three outcomes.
| Stress case | Middle case | Nationwide high case | |
|---|---|---|---|
| Uplift on £1,000,000 | 5% (our stress assumption) | 10% (fourth bedroom) | 24% (bedroom and bathroom) |
| New valuation | £1,050,000 | £1,100,000 | £1,240,000 |
| Loan-to-value before the remortgage | 71.4% | 68.2% | 60.5% |
| New loan at 75% | £787,500 | £825,000 | £930,000 |
| Equity released | £37,500 | £75,000 | £180,000 |
| Works cash not returned | £122,500 | £85,000 | none, £20,000 back |
| Gain in your equity (uplift minus £160,000) | minus £110,000 | minus £60,000 | plus £80,000 |
Two lessons come out of the table. First, at the same 75% loan-to-value you can only borrow back three quarters of the uplift. To get the whole £160,000 back, the house must gain about £213,000, or 21%.
Second, the plan only makes money when the uplift beats the cost. Here that needs the full bedroom-and-bathroom premium. A modest valuation turns the same works into a home improvement you enjoy, not an investment you can draw on.
Not in the table: remortgage arrangement, valuation and legal fees. Not in it either: an early repayment charge if you leave a fixed rate early, or the higher monthly payment on a bigger loan.
The risks that break the plan
Most failed "extend and remortgage" plans fail on one of five points. Each one can be checked before you buy.
- Valuation shortfall. The valuer gives less than you hoped, because of the street ceiling or weak comparables.
- Early repayment charge. The purchase mortgage was fixed for five years and the switch costs thousands.
- Affordability. The new loan is affordable on value but not on income, so the lender says no.
- Rates move. A higher rate at remortgage raises the payment on the whole loan, not just the new money.
- Over-development. The works cost more than the street will pay for, or take the house past what buyers want.
How we help before you buy and after you build
The cheapest time to get this right is before you exchange. That is when the extension options, the consent route and the build cost decide what the house is worth to you.
We start with the address and the sales particulars. We check what can be built: a loft, a side return, a rear or double-storey extension, a mansard or a basement. We tell you the consent route for each, and give you our price per option from our 2026 rates.
Design, consents, build and the revaluation pack
If you buy, one team takes it from there. We design the extension and make the planning or prior approval application, or confirm the permitted development route. We send the party wall notices and make the building control submission.
You get a fixed price for a written schedule of works. That is the document a lender asks for when you apply for a further advance. Extras are priced and signed before they happen, and we advise a 5% to 10% contingency.
At handover you get the building control completion certificate, the electrical certificate and the warranties in one pack. That is the paperwork a valuer and a lender's conveyancer look for at the revaluation. We reply to every enquiry the same working day.
Viewing a house with room to grow? Check what your house can add with us before you offer, and buy on numbers that hold.
Before you offer on a house to extend and remortgage
- Have you checked sold prices on the street for the same house with one more bedroom?
- Is the house in a conservation area or under an Article 4 direction?
- Which extension adds a bedroom and bathroom, and what does it cost at our rates?
- How will you pay for the works before any remortgage: savings, a further advance or a loan?
- Does your purchase mortgage carry an early repayment charge that outlasts the works?
- Will your income pass an affordability check on the bigger loan?
- Do the sums still work if the valuer gives you only 5%?


