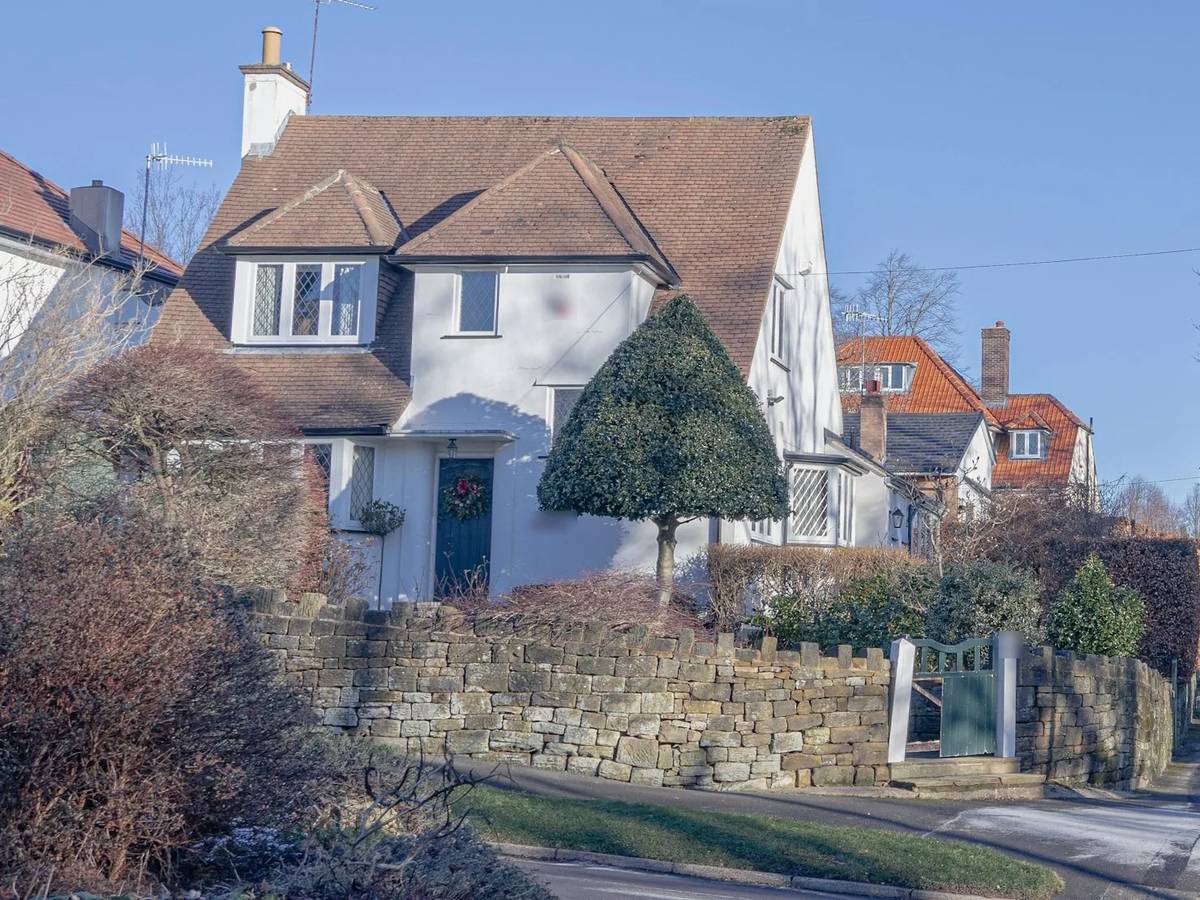
For owners of a plot or a house to replace
Self Build House UK: Planning, Reliefs, Costs and a Worked Example
Sviatoslav JerdetchiiCEO & Founder of Craftex. Updated , 13 min read
The short answer
A self build house is a home you commission on your own plot to live in. With Craftex as your design and build contractor the build costs about £1,780 to £2,925 per m² (our 2026 rates, ex VAT), so a 200 m² house at a standard finish is roughly £356,000 to £396,000, plus the plot and fees.
- You do not need to get planning permission alone: we design the house and run the application with you.
- If you claim before work starts and live in the house for 3 years, you can be exempt from the Community Infrastructure Levy (CIL).
- A VAT-registered contractor can zero-rate the construction of a new home, and the DIY refund covers building materials you buy yourself.
- You pay cost, not market price, so the finished house is often worth more than the plot, the build and the fees together.
A self build house is a home you commission on your own plot, to live in. You choose the design, a contractor builds it, and in England the law gives you reliefs a buyer of a new house does not get.
Those reliefs are worth real money: the Community Infrastructure Levy (CIL) self-build exemption, zero-rated VAT on the build and stage-release mortgages. You do not have to get planning permission on your own either. We design the house, take it through the council with you and build it under one contract.
This guide covers the money first, then planning, each relief, finance, plots and timings. Own a plot, or a house you would rather knock down and rebuild? Book a free plot appraisal and we will tell you what could be built and what it would cost.
Self build house or custom build: what counts
GOV.UK treats self build and custom build as one thing. The Self-build and Custom Housebuilding Act 2015 does not distinguish between them, and neither do the reliefs. What matters is who commissions the house and who lives in it.
| Self build | Custom build | Buying a new home | |
|---|---|---|---|
| Who owns the plot | You | You, often bought from a developer | The developer |
| Who designs the house | You, with your architect | You choose, within a package or design code | The developer |
| Who builds it | You or your contractor | The developer's or your contractor | The developer |
| CIL self-build exemption | Yes, if you claim before the start | Yes, if you claim before the start | No |
| You pay | Cost: plot, build and fees | Cost plus the package price | Market price, developer's margin inside |
A buyer who picks a finished home off-plan, with no say in the design or layout, does not count as a self-builder. Neither does someone who builds to sell or let. The reliefs are for people building a home to live in.
How a self build house makes you money
Self-building is not only about getting the house you want. Done well, it is the cheapest way into a good house, for three reasons.
- You pay cost, not market price. A developer's sale price includes their land margin, finance and profit. On your own plot you pay the plot, the build and the fees, and the difference stays with you.
- Planning permission adds value to the land. A plot with consent for a house is worth far more than the same land without it. You capture that uplift because you hold the land when permission is granted.
- The finished house is often worth more than it cost. That gap is the development margin. You can live in the house and keep it as equity, or sell and take it as money.
The land uplift is large. The latest official land value estimates, made for policy appraisal in April 2019, put residential land in Bromley at £12,860,000 per hectare. Agricultural land in London was put at £25,000 per hectare.
The government warns these figures are not market values for any single site. They still show the point: permission, not the soil, carries the value. In the South East the same study put Elmbridge residential land at £9,280,000 per hectare.
Thinking about a garden plot or a tired bungalow on a big site? Our planning consultants test what the council is likely to accept before you spend on drawings.
Worked example: a self build house in outer London
Here is an illustration for a 200 m² detached house in Bromley, built at our High rate. The plot price, fees, contingency and finance are assumptions to show the method. The build cost uses our rates on 10 November 2026.
| Line | Amount | Note |
|---|---|---|
| Plot | £300,000 | Assumption |
| Stamp duty and legal costs on the plot | £15,000 | Assumption |
| Build, 200 m² at £2,520 per m² | £504,000 | Our 2026 High rate, ex VAT |
| VAT on the build | £0 | Zero-rated new home, conditions apply |
| Design, surveys, planning, warranty, building control | £60,000 | Assumption |
| Contingency | £40,000 | About 8% of the build |
| Finance and insurance during the build | £20,000 | Assumption |
| Borough CIL | £0 | £24,024 if the exemption were not granted |
| Total cost | £939,000 | |
| End value | £1,082,545 | Average detached house in Bromley, August 2026 |
| Development margin | About £143,500 | About 15% of the total cost |
The end value is the Land Registry's average detached price for the borough. A new, larger house often sells above the area average, so check sold prices on your own street before you rely on it.
The Bromley CIL figure is the borough's 2026 residential rate of £120.12 per m² for 200 m². In London the Mayor's levy is charged on top unless you are exempt.
What can go wrong
The margin is real but it is not guaranteed. Four risks move it most.
- Planning refusal. Without consent the plot is worth little more than land. Buy subject to planning where you can.
- Cost overrun. A 10% overrun on this build cuts the margin by about £50,000. Fix the design and price before you start.
- The market. Prices can fall during a build. The example assumes today's average.
- Losing a relief. Start work before the CIL exemption is granted and you pay the levy in full.
The full lines that sit around the build are in our guide to the cost to build a house in the UK.
Self build planning permission, step by step
Most self-builders fear planning more than building. You do not need to do it alone. Our design team and planning team run it with you. Our Development Director has taken more than 10,000 homes through planning in his previous roles.
The route for one new house in England usually runs like this.
- Site check. We read the local plan, the planning history and the constraints, such as a conservation area or flood zone.
- Pre-application advice. Optional and charged by the council, but it shows what officers will support.
- Design and surveys. Drawings, plus the reports the council needs, such as trees, ecology or drainage.
- Application. The council fee has been £610 per new house since 1 April 2026, and £752 is proposed from 8 December 2026.
- Decision. The council should decide a minor application within 8 weeks, unless you agree more time.
- Conditions. Pre-commencement conditions must be discharged before you start on site.
For some small sites, permission in principle is a cheaper first step. It settles the use and the number of homes in 5 weeks, and the detail follows. Our guide to permission in principle explains when it fits.
Section 106 on a single house
National policy asks for affordable housing on major schemes of 10 or more homes. Plans may set it for smaller schemes only in designated rural areas. A single self-build house therefore rarely carries an affordable housing obligation, but check your borough's local plan.
A plot sold off a larger consented site can come with a Section 106 obligation attached. That deed may fix who can occupy the plot, the design code and the timing, and it binds you as owner. Read it before you exchange.
A new house also avoids the Building Safety Levy that started on 1 October 2026. GOV.UK says developments of fewer than 10 new dwellings are exempt, unless the plot is part of a major consented scheme.
The CIL self-build exemption: four steps, in this order
CIL is a fixed charge per m² of new floorspace. Our explainer on CIL and Section 106 covers how it is worked out. For a self-build house you can be exempt, and GOV.UK confirms the exemption covers a home "commissioned from a contractor, house builder or sub-contractor".
Three steps happen before any work starts on site, and one after completion.
- Assume liability. You file Form 2 (Assumption of Liability), or Form 4 if liability sits with someone else.
- Claim the exemption. You file Form 7 Part 1 and wait for the council's written decision.
- Serve the Commencement Notice. Form 6 must reach the council before the start date it states.
- Prove it after completion. You file Form 7 Part 2 within 6 months of the completion certificate.
Start before the council decides your claim and the exemption is cancelled. Miss the Commencement Notice and the council adds a surcharge of 20% of the levy or £2,500, whichever is lower.
After completion you must live in the house as your main home for at least 3 years. Sell it or let the whole house in that time and the levy becomes payable in full. You must tell the council in writing within 14 days.
Great experience from start to finish. Communication was clear, the workmanship was excellent, and the whole project was managed professionally.
VAT on a self build house: zero rate and the DIY refund
Two VAT rules work together, and getting the order wrong loses money. A VAT-registered contractor building a new home for you should charge 0% on the construction. The DIY housebuilders refund then gives back VAT you paid yourself on building materials.
| What | VAT | How you recover it |
|---|---|---|
| Construction of the house by a VAT-registered contractor | 0% | Nothing to recover |
| Building materials the contractor supplies and fits | 0%, inside the build | Nothing to recover |
| Design inside a design and build contract, as a cost of the build | Can be 0% | Depends on the contract wording |
| Architect, surveyor or consultant appointed separately | 20% | Not refundable: they are not building materials |
| Building materials you buy and give to the builder | 20% | DIY refund, one claim within 6 months |
| Carpets, most appliances, fitted bedroom furniture | 20% | Not refundable |
Three points decide whether you lose VAT.
- Make sure the builder zero-rates. HMRC cannot refund VAT a builder charged in error. You would have to get it back from the builder.
- Keep design inside the build where you can. HMRC says that in design and build, consultants' services that are only cost components of the contractor's supply can be zero-rated with it.
- Claim once, on time. The DIY scheme allows one claim, made no more than 6 months after completion.
The DIY refund is only for a home you will live in, or one for a relative. It is not available if you build to sell, to let or for a business. This is general information, not tax advice: confirm your position with your accountant.
How Craftex builds for you while you keep the reliefs
You stay the self-builder. We act as your design and build contractor under one contract with you. We structure the project so you keep the reliefs you are entitled to.
- You own the plot and apply. The planning application, the CIL forms and the register entry are in your name.
- We design it. Our architects draw the house you want, and our builders price it as it is drawn.
- We take it through planning. Pre-application, application, conditions: our planning team runs it with you.
- We sort the CIL timing. We prepare Forms 2, 7 and 6 for you to sign and hold the start until the council confirms the exemption.
- We zero-rate the build. As a VAT-registered contractor we charge 0% on the construction of a qualifying new home, with design inside the contract where the rules allow.
- We feed your lender. We prepare the stage payment schedule and the evidence your lender's surveyor asks for at each stage.
- We hand you the paperwork. Completion certificate, warranty documents and invoices, in time for CIL Part 2 and any DIY claim.
Each relief has conditions we do not control, such as how long you live in the house. We cannot guarantee a relief, but we make sure the paperwork never loses one.
About 60% of our labour is in-house, and an RICS-qualified quantity surveyor on our team prices every line. Holding a quote from another builder? Send it to us. We'll beat it. For the wider model see our design and build service, or book a free plot appraisal.
Self build mortgages, warranty and building control
A self build mortgage pays out in stages as the house goes up, not in one sum. Lenders release money either after each stage is finished and valued, in arrears, or at the start of each stage, in advance.
- Arrears. You pay for each stage first and the lender repays you after a valuation. You need cash or a bridge to fund the gap.
- Advance. Money arrives before the stage, which helps when materials or a frame must be paid for upfront. These products are less common.
We connect you with the lenders we use. We do not give mortgage advice, and we never name a rate.
Help to Build, the government equity loan for self-builders, has closed. GOV.UK says you can no longer apply for properties in England, and it closed to new applicants on 31 March 2025.
Structural warranty and building control
Most lenders lend on a new home only with a structural warranty or a professional consultant's certificate. A specialist self-build warranty also counts as evidence for CIL Part 2, so it often pays twice.
Building regulations approval comes from the council or a registered building control approver. The completion certificate at the end matters three times: for the lender's final release, for CIL Part 2 and for any DIY VAT claim.
Finding a self build plot and the Right to Build register
Every council in England must keep a self-build and custom housebuilding register. You can join if you are 18 or over, a British, EEA or Swiss national, and looking for a serviced plot for your own home.

Councils must grant permission for enough serviced plots to match the demand on their register. They have 3 years from the end of each base period, which runs from 31 October to 30 October. Some councils add a local connection test or charge a fee.
The register is not a plot offer, but it puts you on the council's list. Most plots in and around London come from other routes.
- Your own garden or a side plot. Often the cheapest land, if access and the street scene work. Our guide to backland and garden sites covers the tests.
- A house to replace. Knock down a dated house on a good site and build the house you want in its place.
- Plots with planning. Read the consent, its conditions and any Section 106 first, as our guide to buying land with planning permission explains.
- Serviced plots on larger sites. Sold by developers or councils, often with a design code and a time limit to build.
Self build costs, timescales and selling later
Our build rates per m² for a new house are below. They are construction only, ex VAT and fees. Your fixed figure comes after a survey and the design.
| Specification | Per m² | 200 m² house |
|---|---|---|
| Standard | £1,780 to £1,980 | £356,000 to £396,000 |
| High | £2,270 to £2,520 | £454,000 to £504,000 |
| Luxury | £2,635 to £2,925 | £527,000 to £585,000 |
Try your own size in the build cost calculator.
| Step | Time limit |
|---|---|
| Planning decision, one house | 8 weeks, unless extended by agreement |
| Permission in principle decision | 5 weeks |
| CIL exemption claim | Before work starts on site |
| Commencement Notice | Received before the start date |
| CIL Form 7 Part 2 | Within 6 months of the completion certificate |
| DIY VAT refund claim | Within 6 months of completion |
| Living in the house for CIL | At least 3 years from completion |
The build programme depends on the size, the method and the site. We fix it in the contract before you start, with the price.
If you sell: tax points to check
If the house is your only or main home, a sale is normally free of capital gains tax under private residence relief. Once construction is complete, move in within 24 months of buying the plot. The law then treats the house as your home from the start.
Sell within 3 years and the CIL exemption is clawed back. Build and sell more than once and HMRC may treat the profit as trading income, not a gain on your home. This is general information, not tax advice: confirm the position with your accountant before you sell.
Before you commit to a plot, run through the list below.
Before you buy a plot or start a self build
- Check planning: local plan, history and constraints, or buy subject to consent
- Read any Section 106 attached to the plot
- Price the build from drawings, with a 5% to 10% contingency
- Join the council's self-build register
- Line up a self-build mortgage and a structural warranty
- File CIL Forms 2 and 7 Part 1 and wait for the decision
- Serve the Commencement Notice before work starts
- Keep every invoice for the DIY claim and CIL Part 2


